
Your Guide to Homeownership
Put Your Builder Incentive to Work: Lower Your Monthly Payment

October 2, 2026
Your builder incentive can help lower your monthly mortgage payment. On select Doug Parr Homes, eligible buyers may use available incentive funds toward a temporary mortgage buydown or a permanent interest-rate reduction through a participating preferred lender. The right choice depends on the home, loan program and your financial priorities.
When you are shopping for a new home in Parker or Wise County, the purchase price is only part of the picture. Your monthly payment and the cash you need at closing matter, too. Understanding how to use your Your Way incentive can help you make a more informed decision.
How Can a Builder Incentive Lower Your Mortgage Payment?
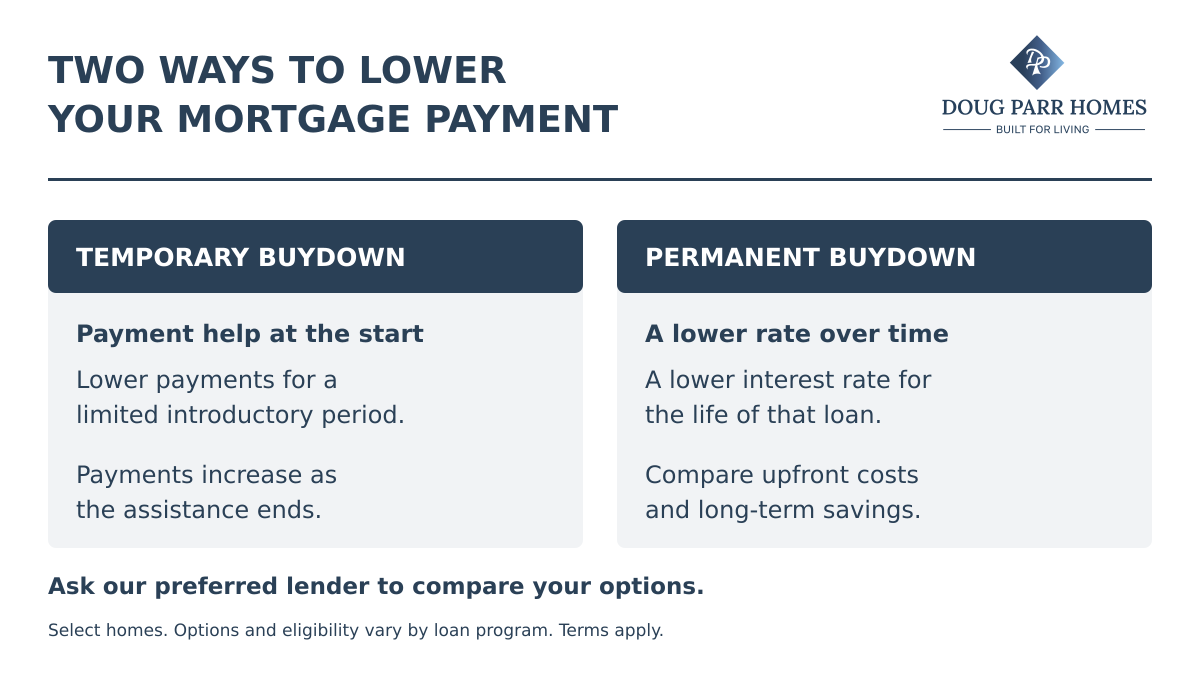
A mortgage buydown uses funds paid upfront to reduce your payment for a limited period or purchase a lower interest rate for the life of your loan. On an eligible Doug Parr home, those funds may come from the incentive already offered with that home.
That means you can explore payment savings using your available incentive. It is an alternative use of the same funds, rather than an additional incentive. Amounts and allowable uses vary by home and loan program. See current Doug Parr Homes offers for available promotions.
Temporary Buydown: Lower Payments as You Settle In
A temporary mortgage buydown helps cover part of your payment during an agreed introductory period. Funds are set aside to make up the difference between your reduced payment and the scheduled payment on the loan.
This can provide extra room in your budget during your first years of homeownership. However, the payment assistance ends. Your payment increases according to the buydown schedule, so ask the lender to show each stage and the full payment after the subsidy ends.
Choose a home that fits your budget at the full payment. Future refinancing is not guaranteed.
Permanent Buydown: A Lower Rate for the Life of Your Loan
A permanent rate buydown uses upfront funds to purchase a lower interest rate for the life of that loan. It may be worth comparing if you prefer ongoing savings rather than introductory payment assistance.
Our preferred lender can walk you through available financing options and explain how the incentive on your chosen home could affect your rate, payment and cash needed at closing.
Compare Your Options Before Choosing
Using an incentive toward closing costs can help preserve your cash. Using it toward a buydown can help reduce your payment. Neither option is automatically the best fit for every buyer.
Ask for a side-by-side comparison showing:
- Cash needed at closing with each option.
- Monthly payments during every stage of a temporary buydown.
- The full payment after temporary assistance ends.
- The rate and payment available with a permanent buydown.
- Total housing costs, including taxes, insurance, applicable mortgage insurance and any HOA fees.
Payment savings depend on the loan amount, rate, term and buydown structure. A personalized comparison gives you a clearer picture than a general savings example.
USDA Financing
Some properties in Parker and Wise counties may qualify for USDA financing. Eligible buyers purchasing an eligible home may qualify for financing with no down payment. Household income, property eligibility and lender requirements apply. No down payment does not necessarily mean no cash is needed at closing.
You can review the official USDA eligibility tool and have your lender confirm whether the home and loan qualify.
Your Way Means Options
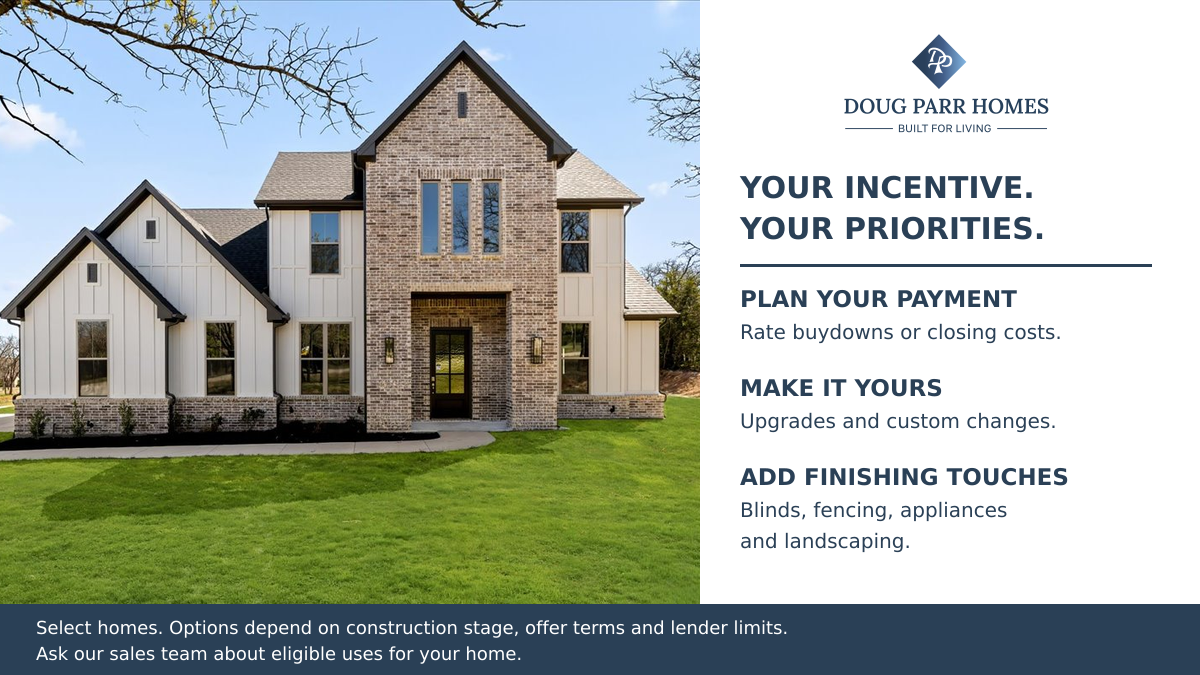
Lowering your monthly payment is one way to put your incentive to work. Depending on the home, its stage of construction and the offer terms, you may also be able to apply eligible funds toward upgrades, custom changes or finishing touches such as blinds, fencing, appliances and landscaping. Ask our sales team which options are available for the home you’re considering and how you can use your incentive toward what matters most to you.
Frequently Asked Questions About Builder Incentives
Can I use my builder incentive to buy down my mortgage rate?
On select Doug Parr Homes, eligible incentive funds may be applied toward an allowable mortgage buydown through a participating preferred lender. The amount and options depend on the home and loan program.
Does a temporary buydown lower my payment for the whole loan?
No. It provides payment assistance for a limited period. Your payment increases according to the buydown schedule, and you become responsible for the full payment when the assistance ends.
Should I choose a buydown or closing-cost assistance?
Compare both with your lender. Closing-cost assistance may help you keep more cash available, while a buydown may help reduce your monthly payment. Review cash to close, the complete payment schedule and total borrowing costs.
Do I receive unused incentive money as cash?
No. Incentive funds apply only to eligible costs within the offer and loan-program limits. Unused amounts are not paid to the buyer as cash.
Put Your Incentive to Work
Make Your Move. Make It Now. Explore available Doug Parr Homes and our North Texas communities, then let us help you compare the incentive and financing options for the home you like.
Contact Doug Parr Homes for a personalized payment comparison or call 940-627-1361. We can connect you with our preferred lender to walk through your options.
Doug Parr Homes. Built for Living.
Incentives are available on select homes at the listed price and require use of a participating preferred lender. Incentives cannot be combined with other offers, promotions or discounts. Incentive amounts are up to the amount offered for the specific home and may be applied only toward allowable costs, subject to loan-program and interested-party contribution limits. Unused amounts are not paid to buyers as cash. Buyers must meet all lender qualifications. Temporary buydowns provide payment assistance for a limited period; payments increase according to the buydown schedule. Loan terms, rates, appraisal benefits, incentives and availability are subject to change or withdrawal without notice. USDA financing requires eligible buyers and properties. Additional terms and conditions apply. Contact Doug Parr Homes and the lender for complete details.
